

How to Cover Payroll in a Slow Month

Sales drop, but payday doesn't move. Here's how to get your team paid through a slow month without scrambling.
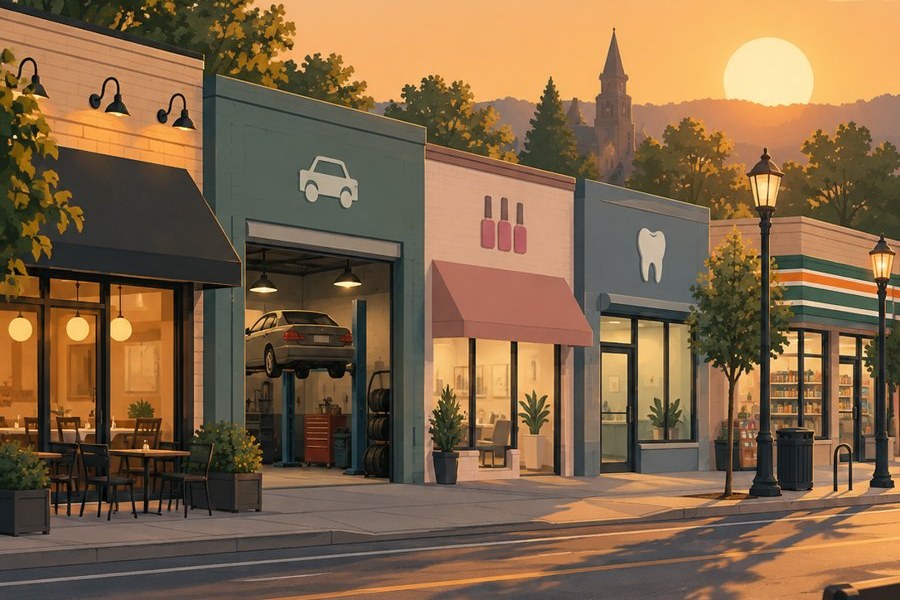
Every business has slow stretches. A restaurant after the holidays, a landscaper in winter, a dental office in August when families travel. Rent and supplies can sometimes wait a few days. Payroll can't. Your team is counting on that deposit, and missing it costs you trust that takes months to rebuild.
This guide covers why payroll gets tight, what to do before a slow month hits, and when outside funding makes sense.
Why payroll is the first bill to feel it
For many small businesses, payroll is the biggest check they write. In a typical restaurant, labor takes about 33 cents of every sales dollar, the same as food. When sales fall 20%, that payroll bill barely shrinks.
Most businesses also don't keep much cash on hand. The JPMorgan Chase Institute studied small business bank accounts and found the median business had about 27 "cash buffer days." That means if no money came in, it could keep paying its bills for about 27 days. Restaurants had the fewest, about 16 days. A quarter of all businesses had 13 days or less.
So a slow month doesn't have to be a bad month to cause trouble. Two or three weeks of lower sales can eat through the cushion right before payday.
You're not alone in this. In the Federal Reserve's latest survey of small employers, covering operating expenses was the most common reason firms sought financing, cited by 56%.
Two things you can't push back
Payday. Many states set how often you have to pay employees, such as every two weeks or twice a month. Moving payday later usually isn't an option. Check your state's rule with the U.S. Department of Labor's state payday table.
Payroll taxes. When you run payroll, you hold back federal income tax, Social Security and Medicare from each paycheck. The IRS expects those deposits on a monthly or semi-weekly schedule. Late deposits cost 2% of the unpaid amount if you're 1 to 5 days late, 5% at 6 to 15 days, and 10% after that, rising to 15% once the IRS sends a notice. Paying your team but skipping the tax deposit is an expensive way to borrow.
Five steps to take before a slow month
- Find your slow months. Pull last year's bank statements and mark the months when deposits dropped. Most slow periods repeat, which means you can plan for them.
- Build a payroll reserve in busy months. Move a set share of every deposit into a separate account, and don't touch it until the slow season. Even one payroll's worth in the bank changes how a slow month feels.
- Match schedules to demand. Trim shifts on your slowest days first, and tell your team early. People handle fewer hours better than a late paycheck.
- Ask about timing before you need it. Suppliers and landlords are more flexible when you call ahead than when a payment is already late.
- Line up funding while things are good. Applying when sales are steady is easier than applying the week before payroll.
When business funding makes sense
Outside funding fits best when the business is healthy and the gap is short and predictable: a slow season you know is coming, a big client who pays late, or a busy season you need to staff up for. It fits poorly when sales have been falling for months with no end in sight. In that case, funding only delays a harder decision.
Zippi is a direct funder, which means we fund you ourselves, not through a broker. Business funding from Zippi goes up to $500,000, with no hard credit check, and funds arrive in hours. You repay a fixed daily or weekly amount, or a share of your daily or weekly sales.
To apply, your business needs:
- At least $20,000 in sales every month. That includes your slow months, so check your lowest month, not your average.
- 12 months or more in business
- 3 to 4 months of recent business bank statements
See how it works for your industry: restaurants, nail salons, dental practices and auto shops.
Quick answers
Can I use business funding to pay my employees? Yes. You can use Zippi funding for payroll, rent, inventory, equipment or other business costs.
Will applying hurt my credit? Zippi doesn't do a hard credit check.
How fast can I get the money? In hours once you're approved, so you can plan around a payroll date.
What if my sales dip below $20,000 in one month? The minimum applies to every month, so that month would keep you from qualifying for now.
Sources: National Restaurant Association (restaurant costs); JPMorgan Chase Institute, "Cash is King" (cash buffer days, 2016 data); Federal Reserve Small Business Credit Survey, 2026 report on employer firms; IRS, Failure to Deposit Penalty; U.S. Department of Labor, State Payday Requirements.
Related posts